Getting denied is frustrating — especially when you need money urgently. Here are the 7 most common reasons Eagle Loan denies applications, and exactly what you can do about each one.
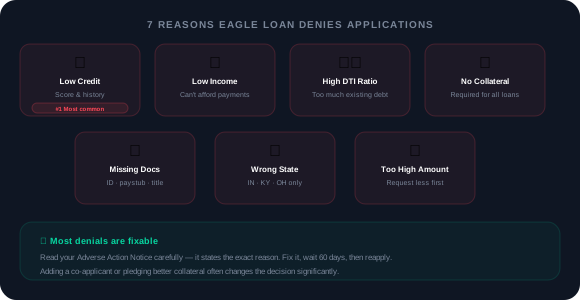
While the lender works with bad credit, there are limits. Very recent charge-offs (within 6 months), active collections, or credit scores below a certain threshold can result in denial.
Lenders need to see you can afford monthly payments. If your income is too low relative to the loan amount, or you've been employed for less than 3–6 months, you may be denied.
If your existing monthly debt payments (car loans, credit cards, rent) eat up too much of your income, adding another loan payment looks too risky. Most lenders want your total DTI under 40–50%.
Every loan requires collateral. If your vehicle has an existing lien from another lender, has very low value, or you have no acceptable assets to pledge, you'll be denied.
Missing a pay stub, expired ID, missing debit card, or incomplete application can result in automatic denial — even if you'd otherwise qualify.
Only residents of Indiana, Kentucky, or Ohio can apply. If you moved or your ID shows an out-of-state address, you'll be denied regardless of creditworthiness.
Asking for $8,000 when your income and credit only support $2,000–$3,000 triggers denial. The lender evaluates whether you can realistically repay the specific amount requested.
This letter (required by law within 30 days) states the exact reason(s) for denial. The specific reason matters — it tells you which problem to fix first.
Visit AnnualCreditReport.com for free reports from all three bureaus. Look for errors — incorrect delinquencies, accounts that aren't yours — and dispute them.
Branch managers have discretion. Asking directly "what would I need to qualify?" often gets you a clear answer — more income documentation, a co-applicant, lower amount, or better collateral.
Multiple hard inquiries in a short period compound the damage to your credit score. Give yourself time to address the denial reason before trying again.
| Alternative | Best for | Key difference |
|---|---|---|
| Credit union PAL | Members with fair credit | Rates capped at 28% APR, no collateral required |
| OppLoans | Very poor credit, all 50 states | No collateral, fully online — but high APR (160%+) |
| Avant | Fair credit (580+ FICO) | Online process, $2K–$35K, 36–60 month terms |
| Secured credit card | Building credit with no loan | Deposit = credit limit, low risk, builds bureau history |
| Borrowing from family | Anyone | $0 interest — but get it in writing to protect the relationship |
Read your Adverse Action Notice — it states the exact reason. Fix it, wait 60 days, reapply. Adding a co-applicant or pledging stronger collateral changes outcomes for most borderline applications.